

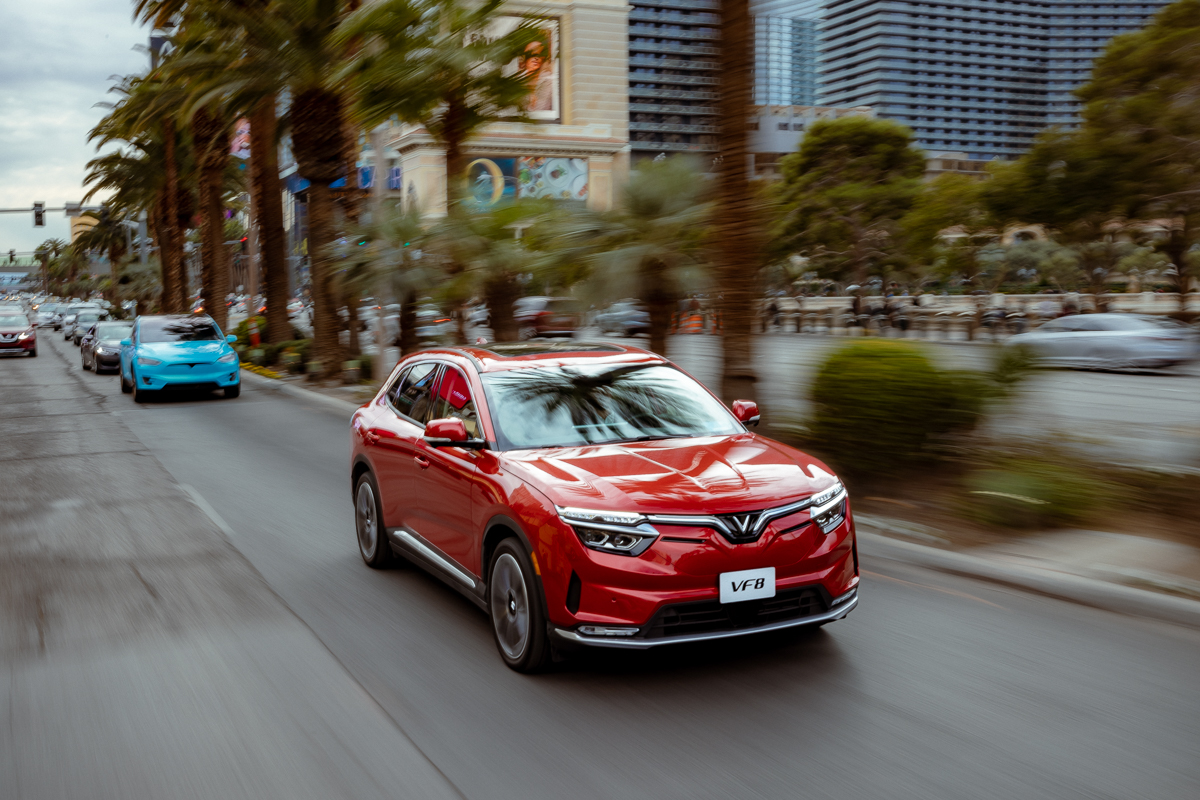
VinFast reported an 85.5% year-on-year increase in second-quarter 2026 revenue to VND30.3 trillion (US$1.2 billion), supported by rising electric vehicle deliveries in Vietnam and growing contributions from India, Indonesia and the Philippines.
The Vietnamese automaker delivered 70,085 electric vehicles during the quarter, up 96% from the same period in 2025 and 20% from the first quarter of 2026. Vehicle sales revenue increased 92.7% year on year to VND28.8 trillion (US$1.14 billion), according to the company’s unaudited results.
Despite its overseas expansion, VinFast remains heavily dependent on its domestic market. Markets outside Vietnam accounted for approximately 11% of second-quarter vehicle deliveries.
Vietnam Remains the Core Market
VinFast said it had led Vietnam’s automotive market for 22 consecutive months and held approximately 38% market share at the end of June.
Demand for new models also contributed to the company’s domestic outlook. The VF 8 and compact VF 2 received more than 12,700 and 28,700 non-binding reservations, respectively. These reservations indicate customer interest but do not represent confirmed vehicle sales.
The range-extended VF Wild has also gone on sale in Vietnam, with international market introductions planned for 2027.
VinFast’s strong domestic position provides a foundation for production scale and sales growth, although its concentration in Vietnam leaves the company exposed to changes in local demand and competitive conditions.
Expansion Across Asian Markets
VinFast is pursuing growth in Southeast Asia and India as it builds its international presence. Among battery-electric vehicle brands, the company ranked first in the Philippines, fifth in India and eighth in Indonesia, according to the figures provided in its results.
However, overseas markets still represented a relatively small share of total deliveries in the second quarter. Expanding beyond Vietnam will be important if VinFast is to diversify its revenue base and reduce its reliance on domestic demand.
The strategy places the automaker in increasingly direct competition with established electric vehicle manufacturers, including BYD, in price-sensitive Asian markets.
VinFast also reported strong growth in its two-wheeler business. Deliveries of electric scooters and e-bikes rose 311% year on year to 286,039 units, adding another source of volume beyond passenger cars.
VinFast Targets a More Capital-Efficient Business
Alongside its revenue growth, VinFast highlighted efforts to improve its financial structure and reduce the capital required to operate its business.
Lan Anh Nguyen, chief financial officer of VinFast, said the company was transitioning towards a more capital-efficient manufacturing model in Vietnam while developing an additional earnings stream.
“We have taken deliberate steps to strengthen VinFast’s long-term financial profile, including the transition to a more capital-efficient manufacturing model in Vietnam and the addition of a complementary earnings stream,”
Nguyen added:
“Together, these initiatives are intended to reduce the capital intensity of our operations, strengthen our consolidated EBITDA and cash generation over time, and provide greater financial capacity to support continued investment in our EV business.”
The company did not disclose gross margin or net loss figures in the results provided. That leaves its underlying profitability and cash requirements difficult to assess from the reported revenue and delivery growth alone.
VinFast has incurred substantial annual losses, while parent company Vingroup has committed more than US$10 billion to support its development. Against that backdrop, the emphasis on capital efficiency and cash generation points to the importance of improving the economics of its operations, rather than relying solely on higher sales volumes.
Growth and Profitability Remain Key Questions
VinFast’s latest results show that it is expanding deliveries and revenue while building a presence in additional Asian markets. Nevertheless, the company’s domestic concentration remains pronounced, with Vietnam accounting for approximately 89% of second-quarter deliveries.
Its ability to translate higher volumes into stronger margins and sustainable cash generation will be a critical measure of progress. Further expansion in India, Indonesia and the Philippines could diversify its sales, but the company will also need to manage manufacturing costs, competition and ongoing funding requirements.
For now, the revenue increase demonstrates commercial momentum, while the absence of detailed profitability figures means the financial impact of that growth remains unclear.


